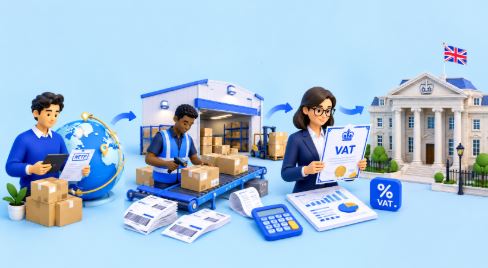
Selling on Amazon UK gives foreign businesses access to the UK market, but there are some VAT regulations depending on whether the business has UK establishments. In the case that a business does not have any establishments in the UK, HMRC treats it as a Non-Established Taxable Person (NETP). Being a NETP means that it does not qualify for the VAT threshold registration applicable in the UK.
What Is an NETP and Why Does It Matter?
A non-Established Taxable Person (NETP) is a person or entity that does not have a UK establishment in relation to VAT. HMRC looks at factors such as where the business is centrally managed and where key decisions are made, to establish whether it has a UK establishment.
Having customers in the UK does not, on its own, mean a business is established there. The difference is significant since the normal VAT registration threshold of £90,000 is not applicable to an NETP. For any business entity in the UK, VAT registration is compulsory where the taxable turnover is greater than £90,000 in the previous 12 months or is expected to exceed £90,000 in the next 30 days.
Where the NETP makes taxable sales in the UK, the requirement for VAT registration arises irrespective of the amount of sales. Registration is required where the business is likely to make taxable sales in the UK in the next 30 days.
Do Non-UK Sellers Get a VAT Threshold?
No. The VAT registration threshold of £90,000 does not apply to a NETP making taxable supplies in the UK. Thus, an overseas Amazon seller needs to register for VAT in the UK even if its UK taxable sales are well below the standard threshold.
This position is still more complex for Amazon FBA sellers. The VAT status depends on things like where the goods are situated at the time of sale, whether Amazon, as the online marketplace, is required to account for VAT, and whether the overseas seller separately makes taxable supplies that trigger its own registration duty.
| Seller type | VAT registration trigger | Threshold |
| UK established business | Taxable turnover exceeds £90,000 in any 12 month period | £90,000 |
| Non-Established Taxable Person (NETP) | First taxable supply or intention to trade in the UK | £0 |
When VAT Registration Is Triggered
Storing stock in Amazon FBA warehouses
Once goods are placed in a UK fulfilment centre, they are treated as being in the UK territory for VAT purposes. Any subsequent sale of those goods is treated as a domestic supply within the UK, and a VAT registration requirement arises as soon as the goods are placed in the warehouse, regardless of how many units are later sold.
Shipping directly to UK customers from abroad
There is the possibility of the VAT charge arising right from the first transaction when selling goods to the customers from foreign stock. Since the £135 threshold has been put in place, most goods of low value when imported to be sold to consumers incur VAT at the time of sale and not at the border, with Amazon serving most often as the deemed supplier of VAT.
Importing goods into the UK
VAT on importation is payable upon clearance of the goods by customs. Where a business is VAT registered, it can take advantage of Postponed VAT Accounting to claim and reclaim the import VAT on its VAT return instead of paying it upfront. If not, then the import VAT becomes an unrecoverable cost.
Believing Amazon’s deemed supplier rules cover everything
Since 1 January 2021, online marketplaces have been legally recognised as deemed suppliers for certain transactions. This means shifting VAT obligations from the seller to the marketplace. This applies specifically to goods in consignments worth £135 or less that are located outside the UK at the point of sale, and to goods already located in the UK at the point of sale. However, it is essential to understand that while the marketplace takes on responsibility for collecting VAT, that does not eliminate the seller’s own obligation to register for VAT once stock has been brought into the UK.
Steps Involved in the Process of Registration
Confirm NETP status. Establish whether the business has no UK establishment and is making, or intends to make, taxable UK supplies through Amazon.
Gather documentation. HMRC typically asks for such information about the applicant as its full legal name, overseas principal place of business address, company incorporation document, tax reference from home country, and description of the proposed trade activities in the UK with indication of the expected date of making the first sale.
Submit the application. File the application. The applications are filed via the HMRC VAT online registration service or VAT1 form. At this step, it is crucial to select the correct entity category (non-UK company) to avoid processing errors, which can take several months.
Respond to verification checks. In many cases, HMRC conducts some additional checks on overseas applicants, requesting them to provide information confirming the trading activity or director’s identity.
Receive the VAT number and certificate. After the application is processed and approved, HMRC sends the applicant a VAT number and the date of the effective registration.
Update Amazon Seller Central. Entering the VAT number in Seller Central is necessary for Amazon to assign the appropriate tax regime to the listing and invoices.
Ongoing Compliance Once Registered
- Submit VAT returns regularly, most often every quarter, even when there are no sales within the UK.
- Ensure that you maintain MTD compliant digital records. Paper submissions through the portal are not allowed anymore.
- Maintain your sales invoices, purchase records, import documents, and transaction reports from Amazon for at least six years.
- Implement the right VAT rate. Mostly, it is the 20% standard rate. Reduced or zero rates also apply to specific product types.
- Utilise Postponed VAT Accounting and handle VAT on import and the VAT return rather than making payment at the time of import.
- Ensure you make your VAT payment on time, since even VAT collected through Amazon does not relieve you of the payment obligation.
Cost of Getting It Wrong
Late registration is subject to the HMRC failure to notify the penalty system, which is a percentage of the VAT that should have been paid.
| Behaviour | Disclosure type | Penalty range |
| Non-deliberate | Unprompted, within 12 months | 0% to 30% |
| Non-deliberate | Prompted, within 12 months | 10% to 30% |
| Deliberate | Unprompted | 20% to 70% |
| Deliberate | Prompted | 35% to 70% |
| Deliberate and concealed | Unprompted | 30% to 70% |
| Deliberate and concealed | Prompted | 50% to 100% |
HMRC also has the authority to assess VAT for up to 20 years from registration failure, in addition to the interest payable. The additional risks come for Amazon itself. An online marketplace that fails to verify whether the seller has a place of business in the United Kingdom and whether the seller complies with the VAT requirements can be held to be jointly and severally responsible for the unpaid VAT of the seller after receiving a notice from HMRC.
Frequent Mistakes Overseas Sellers Make
- Supposing the £90,000 limit is applicable to them while it does not apply to NETPs.
- Waiting till the stock is sold before registering when the stock is placed in the UK warehouse.
- Assuming Amazon’s deemed supplier provision eliminates them from all VAT liability personally.
- Ignoring the cash flow issues with VAT on imports when they do not use Postponed VAT Accounting.
- Using the wrong VAT rates on certain categories of products.
- Lack of proper record-keeping, such that their Amazon settlement reports would not match.
- Incorrect use of cross-border VAT rules when selling digital goods together with tangible goods.
How Reflex’s Amazon Accountants Can Help
Navigating NETP status, Amazon’s deemed supplier rules, and HMRC’s registration processes are quite complex, and doing them wrong can mean backdated liabilities and account suspensions. Our ecommerce accountants work specifically with overseas Amazon sellers to get this right from day one.
- Evaluate whether your business meets the criteria of being an NETP and confirm your proper registration trigger based on your selling scheme.
- Prepare and submit your VAT1 form or register online, and answer all verification queries from HMRC on your behalf.
- Set up Making Tax Digital-compliant bookkeeping systems tailored to Amazon Seller Central reports.
- Reconcile your Amazon settlement report to your VAT return in order to avoid either underreporting or overreporting.
- Advise you on establishing a Postponed VAT Accounting system in order to protect your cash flow related to importing your products.
- Evaluate your product list for applying the proper VAT rates to standard, reduced, and zero-rated goods.
- Submit VAT returns on a quarterly basis and handle any queries from HMRC.
FAQs:
Do I need a UK VAT number before sending stock to Amazon FBA?
Yes. Placing goods in a UK fulfilment centre when you are not established means that you need to register irrespective of whether a sale has been made or not.
Does Amazon collecting VAT under deemed supplier rules mean I do not need to register?
No. Deemed supplier provisions only apply to situations where VAT has to be collected on particular transactions and not other activities, such as imports and holding stock. Registration is still required for other taxable activities like importing or holding inventory.
What happens if I register late?
HMRC can impose a penalty for a failure to notify, which is between 0% and 100% of the VAT payable depending on the nature of the delay.
Can a UK registered company still be treated as an NETP?
Yes. Registration at Companies House does not affect establishment since HMRC considers the actual location of management and control.
How long does UK VAT registration take for overseas businesses?
Processing time can range from several weeks to a few months, depending on whether HMRC needs to carry out further checks on overseas customers. Hence, early registration is needed.
Do I still need to file returns if Amazon already collected the VAT?
Yes. Even after registering, sellers still have to file returns reporting their UK VAT activity, including the deemed supply, regardless of who had the obligation to pay VAT.