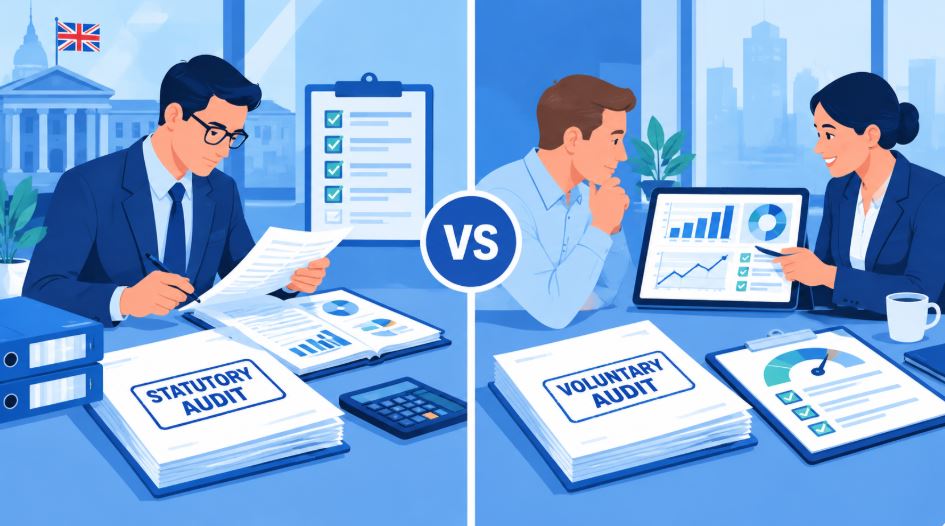
A statutory audit and a voluntary audit can both consist of a very thorough investigation into a company’s financial statements. The key difference between them lies in the reason behind the audit. The statutory audit is obligatory due to statutory requirements or some other binding commitment, whereas the voluntary audit is undertaken voluntarily by an audit-exempt business since independent verification brings business benefits.
The appropriate decision must first be based on eligibility and not preference. The directors must determine if the company is eligible for audit exemption prior to determining whether a voluntary audit or assurance engagement will suit their needs.
What Is a Statutory Audit?
A statutory audit is an independent audit that is mandated by law. The purpose of the auditor is to acquire reasonable assurance that the accounts in general are not materially misstated due to fraud or error and, consequently, give an audit report. A reasonable level of assurance means that the level of assurance is quite high, but it cannot assure the discovery of all mistakes or cases of fraud.
To qualify for small company audit exemption in relation to financial years starting on or after 6 April 2025, a private company needs to satisfy at least two of the following criteria:
- Turnover no higher than £15 million
- Balance sheet total no higher than £7.5 million
- Average of no more than 50 employees
The above-mentioned thresholds depend on the date on which the accounting period begins. Prior periods are still bound by the old limits of £10.2 million in turnover and £5.1 million in balance sheet total, with the same number of employees.
Even meeting the above financial criteria does not guarantee exemption. There is a need for an audit due to the legal form of the business, the regulated activities, the group status, the articles of association, or any other binding obligation. The shareholders who hold at least 10% of the relevant share capital may also ask for an audit in writing.
What Is a Voluntary Audit?
A voluntary audit is also called a non-statutory audit, which occurs in situations where a company is qualified for audit exemption but elects to subject its accounting records to an audit process. In the case where the audit engagement is a full audit according to International Standards on Auditing (UK), then an independent auditor’s opinion will be formed.
A firm can go for a voluntary audit when lending institutions, investors, parent companies, potential buyers, or important clients require audited statements. Such an approach is applicable in cases where there is a need for good governance prior to fundraising, business disposal, rapid growth and entering countries where audits are respected.
The term ‘voluntary’ relates to the reasons a firm can decide to hire the auditor, and not necessarily the quality of service expected. In cases where the stakeholders do not require an audit opinion on the complete set of accounts, another type of assurance engagement can prove more fitting.
Main Differences
| Area | Statutory audit | Voluntary audit |
| Why it happens | Required by law or another binding obligation | Chosen by a company that qualifies for audit exemption |
| Eligibility | The company cannot rely on an available exemption | The company qualifies for exemption but chooses to be audited |
| Core outcome | Independent opinion on the financial statements | Independent opinion on the financial statements when commissioned as a full audit |
| Audit standards | Follows applicable UK auditing and ethical standards | Normally follows the same standards when structured as a full financial statement audit |
| Primary users | Shareholders and other users of the statutory accounts | Owners, lenders, investors, buyers, parent companies or customers |
| Ability to stop | Continues while the audit requirement applies | Can usually be reconsidered for a future year, subject to contracts and stakeholder commitments |
Both audits require enough evidence as well as professional judgement. Neither exempts the directors from their obligations of keeping accounting records, preparing proper financial statements, nor does it exempt them from considering whether the business is a going concern.
When a Voluntary Audit Helps
A comprehensive voluntary audit can be justified where the independent report satisfies a genuine business need.
Raising Finance
The banks and other investors can base their assessment of the company’s profitability, assets, liabilities, and cash flow on the audited financial statements. The exact reporting requirement should be known before the appointment of the auditor since the financer can ask for a full audit, special procedures or any other type of assurance.
Preparing for Investment or Sale
An audit can help to detect poor reconciliations, unbacked balances and accounting decisions prior to conducting due diligence. It is not a substitute for financial and business due diligence, but may help to get more confident about historical financial statements.
Supporting Group Reporting
The UK-based subsidiary can be exempt from audit under UK law while the parent company requires audited figures for consolidation or governance purposes. You should agree on the scope of work, reporting schedule, accounting framework and arrangement with the group auditor upfront.
Strengthening Accountability
An owner-managed business or family business can choose to undergo a voluntary audit in order to get reassurance from external persons such as non-executive directors or minority owners over the financial results of the business. This can become particularly relevant where ownership and control differ between people.
When a Statutory Audit Is the Right Choice
A statutory audit is required when there is a legal requirement for the company to conduct an audit. A voluntary audit is also beneficial when independent verification of the financial statements in their entirety is needed by the shareholders, creditors or investors. The auditor gets reasonable assurance over the accuracy of the financial statements and issues an opinion, but an audit does not assure that all errors and frauds would be detected.
A full audit could be necessary when you need to:
- Comply with a statutory, regulatory or contractual requirement
- Increase assurance over your financial statements in their entirety
- Use your financial information for funding, investment, acquisition or sale purposes
- Generate accurate financial information for various parties
- Improve governance as the company expands and becomes more complex
But a full audit might not be required when the matter pertains to a particular number or process. For example, the creditor may require agreed-upon procedures to verify borrowing base calculations, or management might want specific tests on inventories and sales. The agreed-upon procedures provide factual findings without any assurance conclusions.
How Our Auditors Help
The registered auditors of Reflex Accounting initially determine whether the audit is compulsory or non-compulsory based on the size, structure, accounting period and other stakeholders’ requirements of the firm. After deciding on the appropriate level of audit, the team decides on a realistic timetable, determines what evidence should be gathered, and designs the audit process around those areas that are most likely to hold material misstatements.
Our auditors always communicate information requirements in a clear manner and address accounting problems instantly during the entire process of audit. They give an independent opinion without replacing management duties, and the whole process of auditing should be performed within the scope of relevant ethical requirements regarding integrity, objectivity and independence.
If the audit is mandatory for your company due to any legislation or optional for any financial, investment, or governance purposes, we clearly understand what our target is. Our objective is to perform a well-planned audit and provide reliable reports with minimal disruption.
Frequently Asked Questions
Does a voluntary audit provide less assurance?
Not where it is commissioned as a full financial statement audit under the applicable auditing standards. It can provide the same reasonable assurance; the distinction is that the company chose the audit rather than being compelled by law.
Can an audit exempt company still be forced to obtain an audit?
Yes. Its articles may require one, and members holding at least 10% of the relevant share capital can demand an audit by written notice received at least one month before the financial year ends.
Can a company stop having voluntary audits?
Usually, the board can reconsider the decision for a future period. Before stopping, it should check shareholder arrangements, loan covenants, contracts, group instructions and whether stakeholders continue to expect audited accounts.